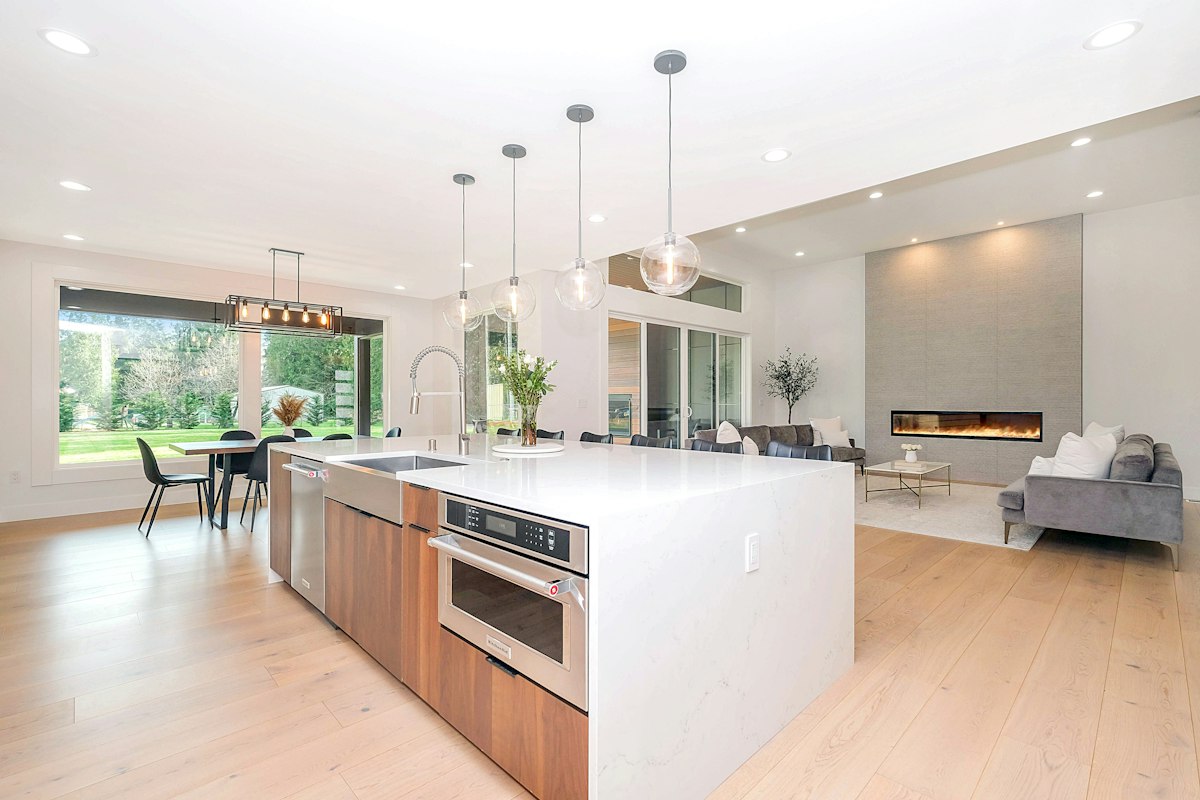
Smart Ways to Fund Your Renovation: Choosing a Kitchen Remodel Financing Option
The kitchen is the heart of the home, but modernizing it is notoriously expensive. Whether you want to replace dated cabinets, install quartz countertops, or completely reconfigure the layout, the price tag can easily climb into five or six figures. Most homeowners do not have that kind of cash sitting idle in a checking account.
Fortunately, you do not have to postpone your dream kitchen until you save up the entire balance. Multiple pathways exist to fund your renovation, each with its own set of interest rates, tax implications, and qualifying requirements. The challenge lies in identifying which method aligns with your current home equity, credit score, and monthly budget.
Related posts
Strategies for Securing the Best Home Loan Interest Rates
Buying a home is likely the most significant financial commitment you will ever make. While the sticker price...
Read more →
Why Hiring an Architect for Home Renovation Protects Your Investment
You stare at the wall dividing your kitchen and dining room, wondering if knocking it down will create...
Read more →
Kitchen Cabinet Renovation Cost: Real-World Budgets, Materials, and Hidden Fees
Walking into a kitchen that feels dated can instantly spark the desire for a remodel. The cabinets are...
Read more →
Debt Consolidation Loan Options: Cut Interest, Simplify Payments, and Clear Balances
Juggling multiple monthly payments across various credit cards, store accounts, and unsecured loans creates constant financial stress. Different...
Read more →This breakdown will analyze the most reliable funding avenues available to homeowners today. We will compare secured options that leverage your home's value against unsecured loans that prioritize speed and simplicity. By the end of this analysis, you will know exactly how to evaluate your financial position and select the right path forward.
Key takeaways
- Secured options like HELOCs and Home Equity Loans offer the lowest interest rates but require using your home as collateral.
- Unsecured personal loans provide fast funding without risking your property, though they carry higher interest rates and require strong credit.
- Tax deductibility is often available for home equity-based financing if the funds are used directly to substantially improve your primary residence.
- Introductory 0% APR cards or contractor promotions can work for smaller, short-term projects if paid off before the promotional window closes.
Home Equity Line of Credit (HELOC)
A Home Equity Line of Credit, commonly known as a HELOC, functions much like a high-limit credit card secured by your home. Lenders typically allow you to borrow up to 80% to 85% of your home's appraised value, minus your remaining mortgage balance. This option is highly flexible because it operates in two distinct phases: the draw period and the repayment period.
During the draw period, which usually lasts ten years, you can borrow funds as needed to pay contractors, purchase appliances, or cover unexpected structural surprises. You only pay interest on the amount you actually draw, not the entire approved limit. This makes a HELOC perfect for multi-stage kitchen renovations where costs are spread out over several months.
However, HELOCs almost always come with variable interest rates. This means your monthly payments can fluctuate based on broader market conditions. If interest rates rise during your repayment phase, your monthly obligation could increase significantly. You must weigh this variable risk against the convenience of having an open pool of capital.
Home Equity Loans
Unlike a line of credit, a Home Equity Loan provides a one-time, lump-sum payout that you repay over a fixed term, typically ranging from five to thirty years. Because the loan is secured by your property, it offers significantly lower interest rates than unsecured credit cards or personal loans. It is often referred to as a second mortgage.
The primary advantage of a Home Equity Loan is predictability. You secure a fixed interest rate, meaning your monthly payment remains identical from the first month to the last. This predictability makes it easy to budget for your kitchen remodel, as there are no surprises when bank rates fluctuate. It is ideal for projects with a fixed, upfront estimate where you know exactly how much cash you need from day one.
The downside is the lack of flexibility. If your contractor uncovers water damage behind your drywall that adds $10,000 to the bill, you cannot simply draw more funds from a Home Equity Loan. You would have to seek additional financing or pay the difference out of pocket. Furthermore, closing costs for home equity products can range from 2% to 5% of the loan amount, which adds to the overall cost of the project.
Unsecured Personal Loans
If you do not want to pledge your home as collateral, or if you bought your house recently and have not built up significant equity, an unsecured personal loan is an excellent alternative. Often marketed specifically as home improvement loans, these products rely entirely on your creditworthiness and income rather than property value.
Because there is no home appraisal or title search required, the application process for a personal loan is incredibly fast. Many online lenders can approve and fund these loans within twenty-four to forty-eight hours. This speed allows you to secure your contractor and order custom materials without waiting weeks for bank underwriting.
The trade-off for this speed and safety is cost. Unsecured loans carry higher interest rates than home equity products. If your credit score is average, you could face double-digit interest rates that dramatically increase the lifetime cost of your kitchen. Additionally, repayment terms are shorter, usually capped at five to seven years, which can lead to higher monthly payments compared to a long-term home equity loan.
Cash-Out Refinancing
Cash-out refinancing involves replacing your existing mortgage with a completely new, larger home loan. You pay off the original mortgage and take the difference in cash to fund your kitchen remodel. This strategy makes sense when interest rates are lower than your original mortgage rate, allowing you to secure a massive amount of capital while potentially lowering your overall interest rate.
For large-scale, luxury kitchen remodels costing $75,000 or more, cash-out refinancing offers a single, streamlined payment structure. You spread the cost of the renovation over fifteen or thirty years, keeping your monthly payments manageable. It also simplifies your financial life by keeping all your housing debt under one single loan.
However, this option is highly sensitive to current market conditions. If you currently hold a historically low mortgage rate, refinancing your entire home loan to a higher current rate just to access remodel cash is financially unwise. You would end up paying a higher interest rate on your entire home balance, not just the portion used for the kitchen. You must calculate the total interest cost across the life of the new mortgage before choosing this path.
Contractor Financing and Retail Credit Cards
Many large remodeling firms and home improvement retailers offer in-house financing options. These are typically managed through partner banks and are presented during the sales pitch. They often feature enticing promotional periods, such as 0% interest for twelve to twenty-four months.
These promotional offers can be highly beneficial for minor cosmetic updates, such as replacing appliances or installing new flooring, provided you have a concrete plan to pay off the balance before the promotional window expires. If you can clear the debt in time, you essentially get an interest-free loan.
The danger lies in the fine print of deferred interest. Many of these retail agreements state that if even one dollar of the balance remains when the promotional period ends, you will be charged interest retroactively on the entire original purchase amount from the date of purchase. Additionally, the standard interest rates that kick in after the promotion ends are often exceptionally high, sometimes exceeding 25% APR.
Evaluating Your Financial Position
To determine the best approach for your specific project, you must systematically evaluate three core variables: your home equity, your credit profile, and the scope of your renovation. Taking the time to analyze these factors beforehand prevents costly refinancing mistakes.
First, calculate your loan-to-value (LTV) ratio. Most home equity lenders require you to retain at least 15% to 20% equity in your home after taking out a loan. If your home is worth $400,000 and you owe $350,000, you only have 12.5% equity, meaning a HELOC or Home Equity Loan is likely out of reach. In this scenario, an unsecured personal loan or contractor financing is your primary option.
Second, review your credit score. A score above 740 unlocks the lowest interest rates across all lending platforms. If your credit is fair or poor, secured options are easier to qualify for because the home mitigates the lender's risk, whereas unsecured loans will either reject your application or charge exorbitant interest rates. Use the following decision matrix to align your project scope with the right funding mechanism:
- Minor Remodels (Under $15,000): Credit cards with 0% APR introductory periods or cash reserves.
- Mid-Range Remodels ($15,000 - $50,000): Unsecured personal loans or HELOCs for flexible spending.
- Major Overhauls (Over $50,000): Home Equity Loans or HELOCs to secure the lowest long-term rates.
Frequently Asked Questions
Can I finance a kitchen remodel with no equity in my home?
Yes, you can finance a kitchen remodel without home equity by using an unsecured personal loan, contractor financing, or a credit card. These options do not require you to use your home as collateral, meaning approval is based on your credit score, debt-to-income ratio, and verified income rather than your property's market value.
Is the interest on a kitchen remodel loan tax-deductible?
Interest on home equity loans and HELOCs is tax-deductible only if the funds are used specifically to buy, build, or substantially improve the home that secures the loan. If you use the equity to completely remodel your kitchen, the interest is generally deductible, but you should consult a certified tax professional to confirm your eligibility under current IRS guidelines.
What is the fastest way to get approved for kitchen financing?
The fastest way to secure funding is through an online unsecured personal loan. Many digital lenders use automated underwriting systems that can approve your application and deposit the funds into your bank account within one to two business days. In contrast, home equity products require appraisals and title checks, which can take several weeks.
What happens if I cannot pay off a secured kitchen loan?
If you default on a secured loan, such as a Home Equity Loan or HELOC, the lender has the legal right to initiate foreclosure proceedings on your home to recover their losses. This is why you must carefully evaluate your monthly budget and ensure your income is stable before securing any debt against your primary residence.
Conclusion
Funding a kitchen remodel requires balancing immediate convenience against long-term financial health. While secured options like HELOCs and Home Equity Loans offer the lowest interest rates and potential tax benefits, they require sufficient home equity and put your property on the line. Unsecured personal loans and promotional store credit provide speed and safety for your asset, but come with higher interest rates and shorter repayment windows.
Before signing any loan agreement, obtain multiple detailed quotes from licensed contractors to establish a realistic budget, including a 10% buffer for unexpected expenses. Compare multiple lenders, look closely at closing costs and fee structures, and choose the financing option that fits comfortably within your monthly household cash flow. With a structured financial plan, you can build a beautiful, functional kitchen that adds genuine value to both your daily life and your home's long-term resale potential.